Join us for the launch of the Sustainability Reporting Standard for Social Housing, an important development in unlocking the significant new private investment needed by the social housing sector.
The launch is the culmination of a 12 month process, initiated by the 17 sponsors and members of the ESG Social Housing Working Group and a consultation which has taken in the views of 250 organisations from across the social housing and financial sectors. We expect more than 60 housing associations, lenders and investors to commit being early adopters of the new Standard.
We’ve lined up some great speakers, including Bob Kerslake (Peabody), Harvey McGrath (Impact Investing Institute and Big Society Capital), Sarah Forster (The Good Economy), Phil Jenkins (Centrus), Paul Hackett (Optivo), Clare Miller (Clarion), Simon Century (LGIM), Natalie Elphicke (UK Parliament), and moderated by Merryn Somerset Webb (Moneyweek).
Please join us for what promises to be a lively and engaging discussion on the benefits of the new Standard.
Registered Providers are under huge pressure to increase spend on fire safety measures and de-carbonisation, whilst simultaneously struggling to support vulnerable tenants, rent arrears and deliver new housing supply. Leading you through this veritable minefield, will be Julian Ashby and Simon Dow, Previous and Interim Chairs of The Social Housing Regulator, expertly held in line by Phil Jenkins, MD of Centrus.
This webinar covered:
What to do in a time of recession; sacrifice development with uncertainty about the cross subsidy model, or land bank?
Should you fill your boots with cheap fixed interest debt or worry about negative inflation and an unsustainable rent formula?
Are money in the bank and development opportunities a winning formula for attracting merger partners or is low debt per unit the honey trap?
Walking the tightrope between delivery and staying on the right side of the Regulator and the Credit Rating Agencies?
“Covid adds new dynamics to stress testing; but it has also illustrated new ways of doing business and new ways of engaging with residents.”
Webinar: Capital Structuring Strategies through Economic Uncertainty
The webinar on Capital Structuring Strategies through Economic Uncertainty took place on the 24th April with speakers Jason Murphy, Gavin Friel & Mark Taheny from the Centrus Ireland team.
Mark Taheny, Director of Centrus in Dublin provides a synopsis in the video below of what was covered in this webinar.
Funding strategy is critical to successful bids in the RESS auction
There is less than 3 months to the revised date for final submissions into the first RESS auction, so focus is now shifting to refining and finalising bid models in preparation for that main event. Funding strategy in relation to both debt structuring and hedging will be a key determinant in the final price bid and delivering on investor returns. There are a wide range of funders who have expressed their support to lend into the new RESS scheme but market uncertainty resulting from Covid-19 means that pricing and risk appetite may be subject to change over the pre-bid and implementation period. Centrus is working with developers and investors in refining the funding proposal that will underpin their final price bid submissions and enhance the delivery of same.
The auction timeline has moved
An important first deadline for RESS passed in the last week of April as qualification applications were submitted. Now that first step is out of the way and initial money has been put on the table in form of bid bonds, it is time for RESS hopefuls to focus on the main event, the auction submission.
Eirgrid recently released its revised timetable which showed limited slippage in the overall timetable given the uncertainty introduced by Covid-19, and includes the following revised dates for some key steps in the auction process. The source of this information from Eirgird can be found here:
Provisional results from the qualification process will be available in early June (9th) and with only a further seven weeks until the closing date of the auction submission at the end of July (28th), the real work on refining and finalising the details of auction bids needs to begin in earnest now.
Focus now on optimising the financing strategy
Bidders were required to submit a letter of commitment from finance providers (equity and/or debt funders) as part of the qualification package submitted in April. The level of commitment required to provide those letters was relatively low.
However, optimising the debt pricing and structure along with risk management of financial exposures (e.g. interest rates, inflation and foreign exchange over the implementation period and project life) will be key inputs into deciding the optimal price to bid into the auction. Therefore, there is a need to ensure that the proposed financing solution is optimised between now and July to produce auction bids that are as competitive as possible and remain viable for the period from auction submission to financial close.
In addition, deliverability of the proposed finance solution will be essential for achieving commercial operations and the flow of RESS funding within the timeframe assumed by bidders. Any unexpected credit / investor requirements or delays in getting the required due diligence to funders will result in delays to financial close and reduced RESS revenues with knock on impacts for investor returns.
Consider the wide range of options available
Our discussions with clients and the market reveal a range of debt solutions are under consideration, ranging from project finance on an individual project and portfolio basis, corporate balance sheet and in some instances short term / bridging facilities through the construction stage – with the appropriate debt structure being complemented with hedging solutions in respect to interest rates, inflation and foreign exchange in order to meet shareholders’ return and risk requirements.
Centrus works with the Irish and European banks who have been key funders of renewable projects in REFIT and all remain committed to continuing to support the sector under RESS. In addition, we have strong relationships with a range of bank and institutional funders from across Europe and beyond with experience of lending into renewable auction processes in the UK and Europe including established models for solar funding. Many are keen to build on that expertise to support developers in the evolving RESS support market and are actively seeking opportunities to build relationships with clients in Ireland. Given the range of funding options available, bidders should undertake a detailed review of the pricing and structures on offer to ensure the best fit in terms of their bid model.
…But beware of Covid impacts other than just the auction timeline
However, it is important to note the context in which the auction bids are being prepared as Covid-19 not only impacts on construction programmes and supply chain logistics in the short term (e.g. pricing for solar panels are likely to be impacted by supply-demand dynamics and USD exchange rates while turbine pricing is more likely to be impacted by increased supply costs) but is also significantly changing the financing landscape.
To date funders continue to confirm their strong preference for lending into the green sector and indicative pricing (if given) has typically referenced pre-Covid levels from February as a baseline. However, as elsewhere in the banking sector, existing relationships and/or large developers with strong pipelines could be favoured over new/smaller clients and pricing will be reassessed when term sheet commitments are required. Based on a substantial widening in credit spread movements and market volatility over recent weeks, pricing today would show that loan margins have moved wider while changes in risk appetite will feed through to the range of funding structures being made available. In addition, market expectations for long term interest rates and inflation, energy market forecasts and USD exchange rates are all in flux as the impact of the pandemic is felt in Ireland and elsewhere. All these changes in inputs will need to be understood and factored appropriately into the bid price model.
The auction process requires that the financing solution underpinning the bid price is deliverable in terms of both pricing and the risk appetite of the funder over the approximate 12-18 months implementation period. Allowing funders the necessary time to get approvals for projects in the new RESS support regime in the context of increased and ongoing market uncertainty due to Covid-19 means engagement with a range of lenders to get the most competitive pricing and fully committed termsheets in advance of final bids needs to start now.
Crucial next steps for a successful bid price
Achieving the appropriate balance between being as competitive as possible in an auction process and delivering investors’ required returns in line with their risk appetite is always a difficult task. In the context of the upcoming RESS auctions, this will be further complicated by (i) the need to develop a model that optimises the bid price into a “pay as bid” auction within the constraints of the RESS support structure (e.g. no inflation, zero floor in periods of negative pricing, etc.) and (ii) the Covid-19 context which is leading to concerns regarding the pricing and deliverability of funding solutions over the auction period as well as increased uncertainty around a range of key inputs from inflation to foreign exchange pricing, electricity market curves and the timing and costs of project delivery.
Understanding the full range of funding providers with an appetite to lend into the developing RESS market along with the debt structures and hedging solutions that can be deployed for risk management is a critical next step in the bid management process. Centrus is helping developers and investors in refining the funding proposal that will underpin their price bid submissions and enhance delivery of same through the following:
Financial strategy including optimisation of debt and equity structures
Debt funding options appraisal to ensure competitive pricing and deliverability
Negotiation of funding and commercial contracts alongside hedging strategy and benchmarking of debt and swap pricing
Interest rate and foreign exchange hedging to mitigate risks on capital costs and project returns
The passing of the Conservative leadership baton (or rather the poisoned Brexit chalice) from Theresa May to Boris Johnson has perhaps brought with it a shift in emphasis back towards the traditional ideological safe ground of support for home ownership over rent. This was evident at the recent Conservative Party Conference, when the latest Housing Minister, Robert Jenrick, announced that housing association tenants will be given the right to buy 10% of their homes – on an automatic basis for new homes and under voluntary arrangements in relation to existing housing stock, the so called “Shared Ownership Right to Buy”.
The announcement unleashed the sort of response usually reserved for somewhat “on the hoof” policy statements which one can’t help but imagine must be dreamed up late one evening before the conference by special advisors writing ministerial speeches and seeking a punchy headline. It is also worth noting that the voluntary right-to-buy scheme explored by the Cameron administration has not really gained traction.
Commentators have highlighted the demand-side weaknesses of the idea, including:
1) Why would rational people voluntarily take on full repair and other leaseholder obligations for the upside of a 10% share in house price appreciation (see recent cases of leaseholder exposures to fire retrofitting costs)?
2) The cost of servicing the 10% mortgage – along with the rent on a shared ownership basis (2.75% on value?) – could easily exceed the 10% saving the resident would make on their (sub-market) rent – how many people is this likely to be relevant to?
3) The market for shared-ownership mortgages is already relatively thin – why would lenders bother for just 10% shares vs the usual minimum of 25% (although they could come under political pressure to support a Government Initiative)?
4) For people who can access and service a shared ownership property, why wouldn’t they just do so in the market?
Putting to one side the question of whether this presents an attractive proposition to housing association residents, it throws up complexities in relation to the debt funding model traditionally utilised by HAs. These include:
a. Lenders have, to varying degrees, pushed back on the inclusion of material amounts of shared ownership within security portfolios, partly because of uncertainty over underlying security value and the process of realisation under a default and partly as a result of the administrative burden associated with monitoring and removing from charge as staircasing increases.
b. The typical approach taken by bank lenders has been to cap the amount of shared ownership that borrowers can include within a security portfolio for a given loan. Institutional investors have been somewhat more relaxed but have still often sought to limit levels.
c. Again, ignoring the question of uptake, which we consider would be limited, in the event of this policy being implemented, all new build property would be subject to Shared Ownership Right to Buy which lenders would see as being an inherently less stable form of security than traditional social or affordable rented. This would likely lead to greater scrutiny of forecasts and stress tests around different stair-casing scenarios (as lenders seek to quantify a new business risk for HAs) as well as changing the way in which HAs might manage interest rate and refinancing risk. If borrowers considered there to be an inherent risk of higher stair-casing then this would likely reduce their appetite for large volumes of long-term fixed rate debt with expensive spens/modified spens type breakage costs, which appears potentially a move towards a riskier funding profile.
d. In return for more leeway on the inclusion of property exposed to stair-casing, banks may look to tighten up interest cover covenants and raise asset cover thresholds, particularly where shared ownership stock exceeds certain levels, or to shorten tenors on new funding even further.
e. Where HAs sought to enter into voluntary arrangements in respect of existing stock, which was already charged under previously arranged loan agreements, it is possible that this would trigger renegotiation of these loan agreements. Depending upon the commercial terms of these agreements, HAs may be exposed to a worsening of economic terms as well as covenants.
In summary, the proposed policy, which we believe to be limited in its appeal to HA residents, would create a number of uncertainties in relation to the existing debt financing model for HAs.
While we don’t believe it to be material in terms of the market’s willingness to extend credit to the housing sector, we do believe that it has the potential to increase actual and perceived risk on the part of lenders and therefore to increase pricing and tighten security and financial covenants, the combination of which could lead to reduced borrowing capacity and output. This does not mean that there is no merit to any form of the policy, but it does mean that it should be considered carefully and in a way, which is sensitive to the range of existing funding bases out there in the market.
Visit the Residential & Real Estate page to find out the wide range of services that Centrus provides to Housing Associations across the UK and Ireland.
How the right technology solution can support an effective commodity hedging and risk management strategy
Over the past decade, many firms were forced to reassess their approach to risk management in face of increased price volatility across international commodity markets, in particular, due to the dramatic drop in oil prices between 2014 and 2016.
Implementing more effective hedging strategies has frequently met the objective of reduced price risk and earnings volatility, and the impact of these strategies has often become a competitive advantage to the companies concerned. When designing a hedging strategy, a series of steps need to be taken, starting with the key strategic objectives of management and shareholders. Once the right strategy has been arrived at, robust and bespoke technology solutions are required to be able to deliver it.
An implementation stage seeks to collect the relevant risk data and metrics across the business so that management and decision making can be performed. Then the ongoing process is a setup that combines appropriate quantitative analysis daily alongside market intelligence. There are clear benefits in decision making being done in one place as opposed to scattered across organisations, and the right technology solution can enable this.
Risk management process – building a framework and implementing a strategy
Technology as an enabler
Although the benefits of a holistic hedging strategy and framework are widely recognised, there are also innumerable examples of organisations making costly decisions due to the lack of coordination between different strands of their business e.g. a department undertaking expensive financial hedges unaware of natural hedges already in place or exposures in their pension schemes, leading to an opposite increase of the net exposure instead of the desired reduction.
As organisations grow in complexity, with multiple departments undergoing their own risk management, such risks only increase. Advances in technology have made it easier to combine exposures and the related hedges within a single monitoring department, often across traditionally separated sector types, such as currencies and commodities. Using spreadsheets to manage such processes would normally be sufficient on a small scale but as a business grows in complexity, spreadsheets become impractical and a risk in their own right. Technology in this instance can be used effectively to aggregate demand forecasts and actuals and determine the net exposure to each different factor.
The team in charge of risk management normally receives inputs from different departments and enters these into a master system, which then allows the team to hedge defined, relevant net risk exposures, and suitably procure the appropriate hedging transactions in the market.
Such a shift in technology has driven changes in attitudes in the organisational design as the hedging role has often fallen to treasury. This has resulted in FX and commodity risk management becoming increasingly relevant in a treasurer’s agenda, a markedly different view compared to less than a decade ago. A sophisticated platform that can run portfolio risk analysis, as well as deal with daily operations, can add significant value to the treasury function.
Implementation challenges
There is still a gap between setting a hedging framework supporting the consolidation of risk management in one department and the reality of organisations often being riddled with overlapping legacy systems across different departments. This can result in inefficiencies, duplication of work and a heightened level of undue risk which breed implementation stage challenges.
Centralisation of tasks both simplifies the business infrastructure and reduces cost but requires careful planning. It can often be an intense project management process that drains significant time and resource, and a barrier to a successful implementation of the optimal hedging framework. Centrus has supported such system development, and provision of market data successfully delivering efficiencies to organisations, streamlining projects by integrating and simplifying system architecture and driving valuable efficiency savings.
However, a system solution is only an enabler. In the first instance, a properly supported and aligned risk management framework is the essential starting point from which to develop an effective hedging strategy. Both elements require the buy-in of senior management, without which even the best system will struggle to make a difference. As always, a hedging strategy is only as good as the people and management driving it. An effective technology and system partner can make the difference in ensuring that the selected strategy can be successfully and effectively delivered in a business-enhancing fashion.
Technology has also driven other corporate changes:
Transparency: Boards and executive teams demand better visibility of the company’s net exposures, often in real-time, as a response to increased volatility in markets and demand for transparency.
Regulatory: Businesses, mindful of the changing regulatory environment such as the introduction of MiFID II, EMIR and Dodd-Frank which may cause an impact on non-financial businesses, are often using technology to produce more comprehensive and detailed disclosures.
Hedging Strategy: Technology is featured in business review processes to fine-tune or re-establish existing hedging frameworks analysing the information on the prices achieved and the performance against targets.
Case Study: Risk Reporting & Derivative Valuation Services for a Major Airline
Previously had 4-5 TMS and Trading system licenses (FX and Fuel)
Risky and intensive spreadsheet calculation and reporting
Complex valuations approximated by substandard systems
Desire to streamline and upgrade risk management
Centrus designed the following solution for a global airline:
Set-up automated feeds of business exposures and hedging portfolio to Centrus’ platform, removing existing systems
Customised reporting deliverables
Daily Dashboards – Daily MTM Valuations / Collateral calls – Potential Expected and Future Exposure (EPE/PFE) – Daily Hedging Position for FX and Fuel: Open exposures / hedged positions across time
Value at Risk: Application of different hedging strategies to VaR calculations – Weekly cash sensitivity reporting based on VaR outputs (CFaR)
Enhanced Reporting Daily dashboards received early in the morning with up-to-date portfolio position and valuation information.
Reduced Cost savings from system replacement and removal of internal spreadsheet processes.
Pertinent Advice: Centrus and the airline are working closely together to ensure hedging strategy is fit to wider internal goals and appropriately communicated to internal stakeholders, keeping up to date with the latest market practices.
Centrus Risk
Centrus Risk provides independent valuations and risk analyses of complex OTC derivatives and structured products. Centrus has both quantitative and technological expertise in delivering valuations, analyses and specialised reporting. Centrus Risk system framework consists of sophisticated rules engine which allows us the flexibility to adapt to new requirements and market demands. We believe it’s imperative that this service is coupled with unparalleled customer support consisting of professionals from diverse backgrounds, such as accountants, treasurers and derivative specialists.
Key Benefits
Automated Financial Disclosures Reports – Information for your business and accounts in the format you require
Automated Hedge Accounting
Automated MTM Reports
Valuations & Cashflows on Complex Positions
Potential Future Exposure (PFE) Calculations
CVA/DVA/KVA/FVA
Hedging Advice and Analyses
Value at Risk (VaR) calculations
EMIR Reporting
About Centrus
Centrus offers leading derivative, debt and treasury technology and advisory services for Corporates, Banks, Custodians & Fund administrators, Insurance companies, Pension, Debt & REIT funds. Our highly experienced team has a wide variety of backgrounds enabling us to provide our clients with expertise across: Treasury and Derivatives, Systems, Reporting & Valuation Services, Capital Raising and Corporate Finance.
For more information, please contact Gilles Bonlong, Director – Centrus
In early July, Centrus gathered over 100+ housing sector clients and professionals for a half-day conference in Central London to discuss the theme: “Housing sector: a new financial landscape?”
The day started with a panel of presenters focussed on the current and future financial landscape, specific to the housing sector and venturing beyond. Delegates were addressed by Anne Costain, Director of Finance, IT and Procurement at Radian Housing, followed by Lisa Pinney, Executive Director of Resources at POBL.
“Radian and Pobl are leading providers of affordable housing in England & Wales respectively. Both have achieved significant organic growth but they also have in common group structures and legacy funding challenges arising from combination with other housing associations. Anne and Lisa shared their experiences, where both organisations are on a journey towards improving their treasury portfolios, supported with corporate finance advice provided by Centrus.”
Paul Stevens, Managing Director – Centrus
The next session of our event debated the role of Equity and Profit and what the risks and opportunities are arising from commercial activities. The Centrus team was joined by Will Perry, Assistant Director at the Regulator of Social Housing, alongside Christophe Parisot, EMEA Head of Public Finance at Fitch Ratings.
“The session highlighted the contrast in views from the different stakeholders with Jon adding insight into the various guises of equity and how these could offer a range of interesting options to the sector. Will pointed out that there has not been any substantive successes from the for-profit providers yet and Christophe setting out the challenges from a rating perspective. Christophe also gave some insightful commentary around how the sector should be able to weather the credit impact of a potential (or eventual) Brexit.”
Barry Greyling, Director – Centrus
Our third panel brought the risk management subject into focus and the Centrus view on the financial markets, data management and reporting solutions. We heard Conor O’Flynn, Managing Director of Centrus Analytics, discuss the ideal 80/20 ratio of time spent in transactional versus strategic activities and how housing associations should look to start their unique journey to achieving an 80/20 balance between managing drivers and managing transactions.
Our final debate raised the question: what could funding solutions look like in the future, in the context of current and emerging trends?
“These are exciting times, with a positive investor landscape for housing associations to enter the institutional funding market. We are seeing an increased number of investors entering the sector from a variety of funding structures. This creates a wider range of funding options for borrowers to choose from.”
Maria Goroh, Director – Centrus
Dominic Brindley from NatWest discussed the sector evolution and the emerging challenges around ESG bonds and, the prospect of the transition between LIBOR-SONIA and Michael Carr, Director at National Australia Bank, and Amelia Henning, Director at Barings brought insight into how the sectors evolution and changing risk profile is viewed by new and expanding lenders.
“The last panel session highlighted the strong demand for housing debt from investors but also sounded a cautious note around lender perceptions of increased commercialisation. Other highlights included a discussion on the potential appetite of some investors for SONIA linked debt and how regulatory headwinds in the pension sector may provide ESG compliant bond pricing benefits for the housing sector. For providers looking to access debt the current environment is highly attractive, but the panel outlined the growing complexity and diversity of options facing borrowers with a recommendation that approaches to the market should be appropriately considered and structured.”
John Tattersall, Director – Centrus
The Centrus Housing team is very pleased with the success of our first conference and hope it provided valuable insight to all attending.
To find out more please contact Paul Stevens, Managing Director – Centrus
Following the launch of the recent White Paper UK Social Housing – Building a sector standard approach to ESG reporting, we hosted the first in a series of webinars designed to discuss and develop the ESG reporting standards.
This webinar explained the drivers behind developing a standardised set of ESG criteria, and explored how it could benefit both housing associations and investors.
Chair: Luke Cross, Social Housing, Editor, Social Housing
Speakers: Phil Jenkins (Manager Director, Centrus), Gareth Francis (Director of Treasury and Corporate Finance, Clarion Housing Group), Anthony Marriott (Head of Treasury/Finance, Peabody), Mark Davie (Director – Fixed income, M&G), Marcos Navarro (Director, Housing Finance, Commercial & Private Banking, NatWest), Sarah Forster (CEO, The Good Economy).
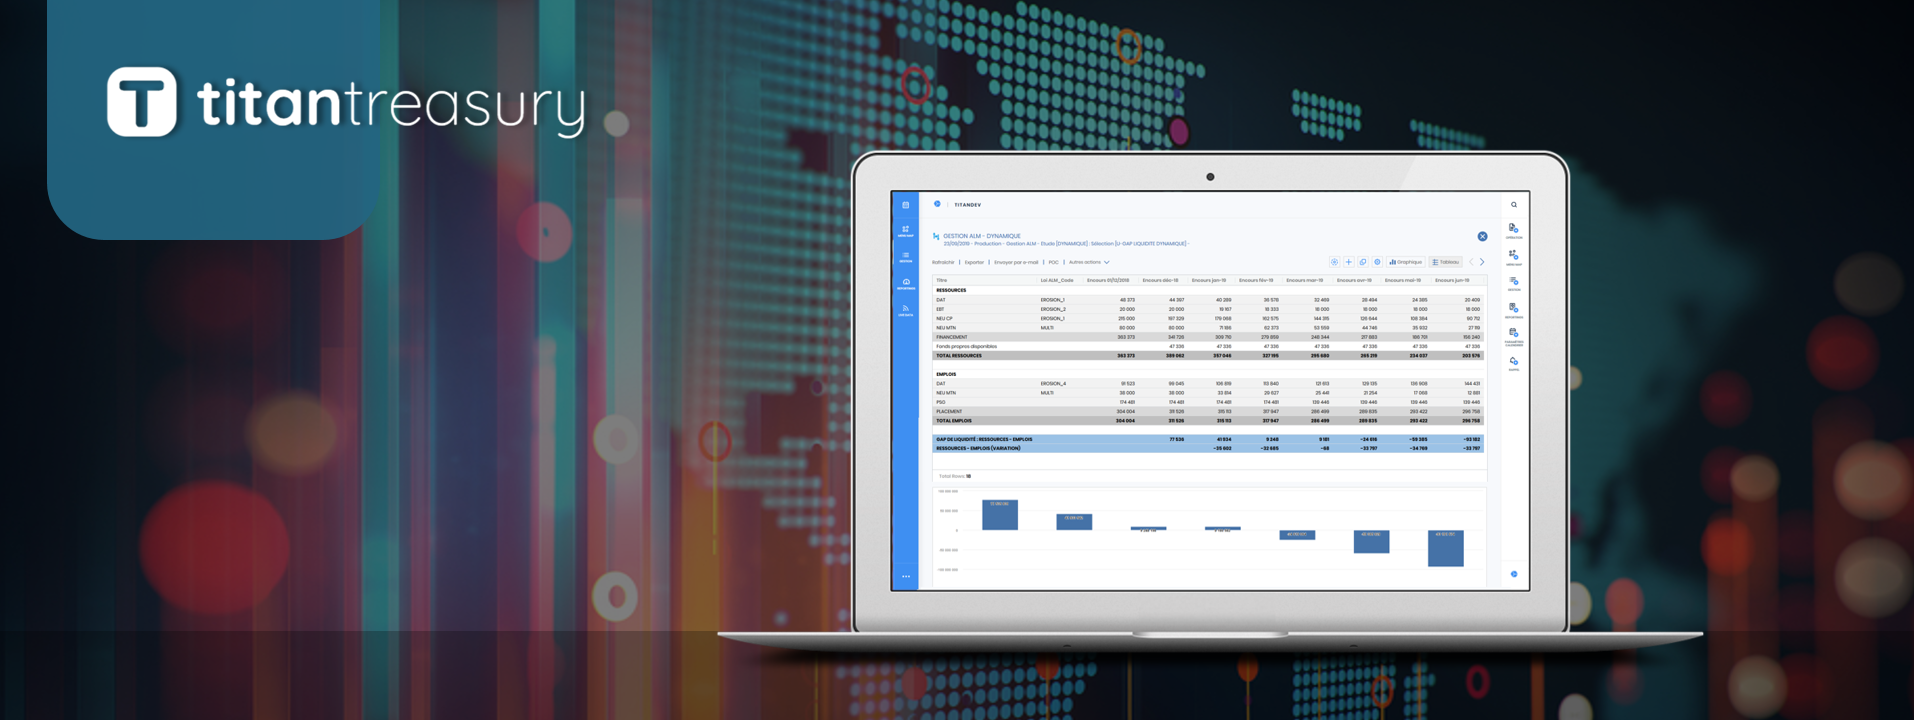
These are the five reasons why titan treasury is in Deloitte’s top 8 TMS solutions: delivery model, deployment time, frequency of updates, functionalities, but most importantly… because of it’s focus on people.
The Centrus Analytics and 3V Finance teams are very pleased to see that, after a few months of interviews and detailed answers to an extensive Request for Proposal (RFP), titantreasury has made it to Deloitte’s list of 8 leading Treasury Management Systems available to the UK market.
The Deloitte Treasury Technology Market Intelligence 2019 report, published this May, aims to help businesses map out their treasury strategy and requirements in order to find the best treasury management system vendor to match these needs and beyond.
The report is a market based review of today’s and tomorrow’s Treasury technologies and how their implementation, which could be seen as a challenge to most organisations, can actually be an opportunityto deploy creative solutions that deliver simple, transparent and efficient Treasury processes.
The report maps out the current Treasury Management System’s vendor market. Deloitte has surveyed 8 leading vendors, covering 14 individual systems, based on what the consultancy firm has observed most often amongst their clients.
The key comparison criteria between vendors were (1) delivery model, the (2) average deployment time, the (3) frequency of major platform upgrades and the (4) level of functionality coverage.
See below how titantreasury performed in each of these criteria:
1.Delivery model
titantreasury gives the users the delivery options to choose from that best suits their organisational needs.
2. Average deployment time
Disciplined communications, close project management and exceeding client expectations are key to sucessfully delivering a software between 3 to 5 months on average. We have pushed the limits on this by bringing our average implementation time in 2019 to less than 2 months. A detailed kick-off phase of understanding the client’s requirements, continued and frequent communications to align expectations, trasnparency around every step of the way and working together is what enables us to deliver quickly and efficiently for our clients.
3. Frequency of major platform updates
Upgrading once a year means users can plan ahead for major platform upgrades, request training for new functionalities, and the upgrades are free.
Each upgrade is communicated in advance through a client release detailing new functionalities and, if they are interested in any of the new functionilites, users can schedule the time
they suit them best for a training session. The client is the pilot for the upgrades.
4. Level of functionality coverage
There is a variance amongst the functional coverage but again with titantreasury this is driven by the client and their constraints. We believe in giving options to the clients to ensure the solution matches their needs, overcome their constraints and deliver on their objectives.
Beyond that we believe that there is a 5th reason why titantreasury stands out from the best TMS vendors available.
The 5th is the most important reason in our view. In the words of Deloitte’s own experts:
“Companies should make vendor and technology decisions that ‘best fit’ their individual businesses. This includes a vendor that understands your requirements, has the right deployment model, can integrate best resources of both teams and provides an application where the ‘feel and fit’ is in tune with the existing application landscape.”
5. Understanding the client and working as an extension of their team
At Centrus we believe in putting people first. That means understanding the client and working together every step of the way are essential part of how we work.
Although this is a key criteria when chosing the best TMS solution, it is a very difficult one to measure with a technical survey and RFPs like what has been done historically. However, for Centrus this is a key part of the project delivery, and our team works closely with clients, asking for feedback and quickly implementing the necessary actions to get to the best outcome possible.
titantreasury empowers treasury professionals to focus on value.
We help clients such as Pennon Group, Orbit Group, Irwell Valley Homes, A2Dominion, Carrefour, Accor Hotels and many others to make their lives easier.
If you’d like to like to book a demonstration with our team, please contact Gilles Bonlong, Director – Centrus
You can download the original report at Deloitte’s website clicking here.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you agree to our Privacy Policy
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.